Would You Let $80 a Month Hold You Back from Buying a Home?

December 1, 2025

A lot of buyers are stuck in “wait and see” mode right now. They’re watching rates hover a little above 6% and thinking, I’ll buy once they hit the 5s. Because who doesn’t want a better rate?
But here’s the thing: that 5.99% number might not save you as much as you think.
Affordability is still a challenge. There’s no question about that. But the market has given savvy buyers a head start. Mortgage rates have already come down over the past few months. And the drop we’ve seen saves you more than you’d think.

How Much You’ve Already Saved, Without Realizing It
Let’s put some real numbers to it. Rates peaked for the year in May when they inched above 7%. But since then, they’ve been slowly declining. Now, they’re sitting in the low 6s. And while that may not sound like a big deal, that change translates to real dollars.

According to data coming out of Redfin, the typical monthly payment on a $400,000 home is already down almost $400 since May.

That means if you’re buying a home now, you’re saving hundreds of dollars every month compared to what you would have been able to get earlier this spring. That’s real money that makes a real difference for buyers who paused their plans because they thought homeownership was out of reach.
And while it may be tempting to wait even longer to see bigger savings, that’s a gamble that could cost you. Here’s why.

Where Experts Say Rates Are Headed
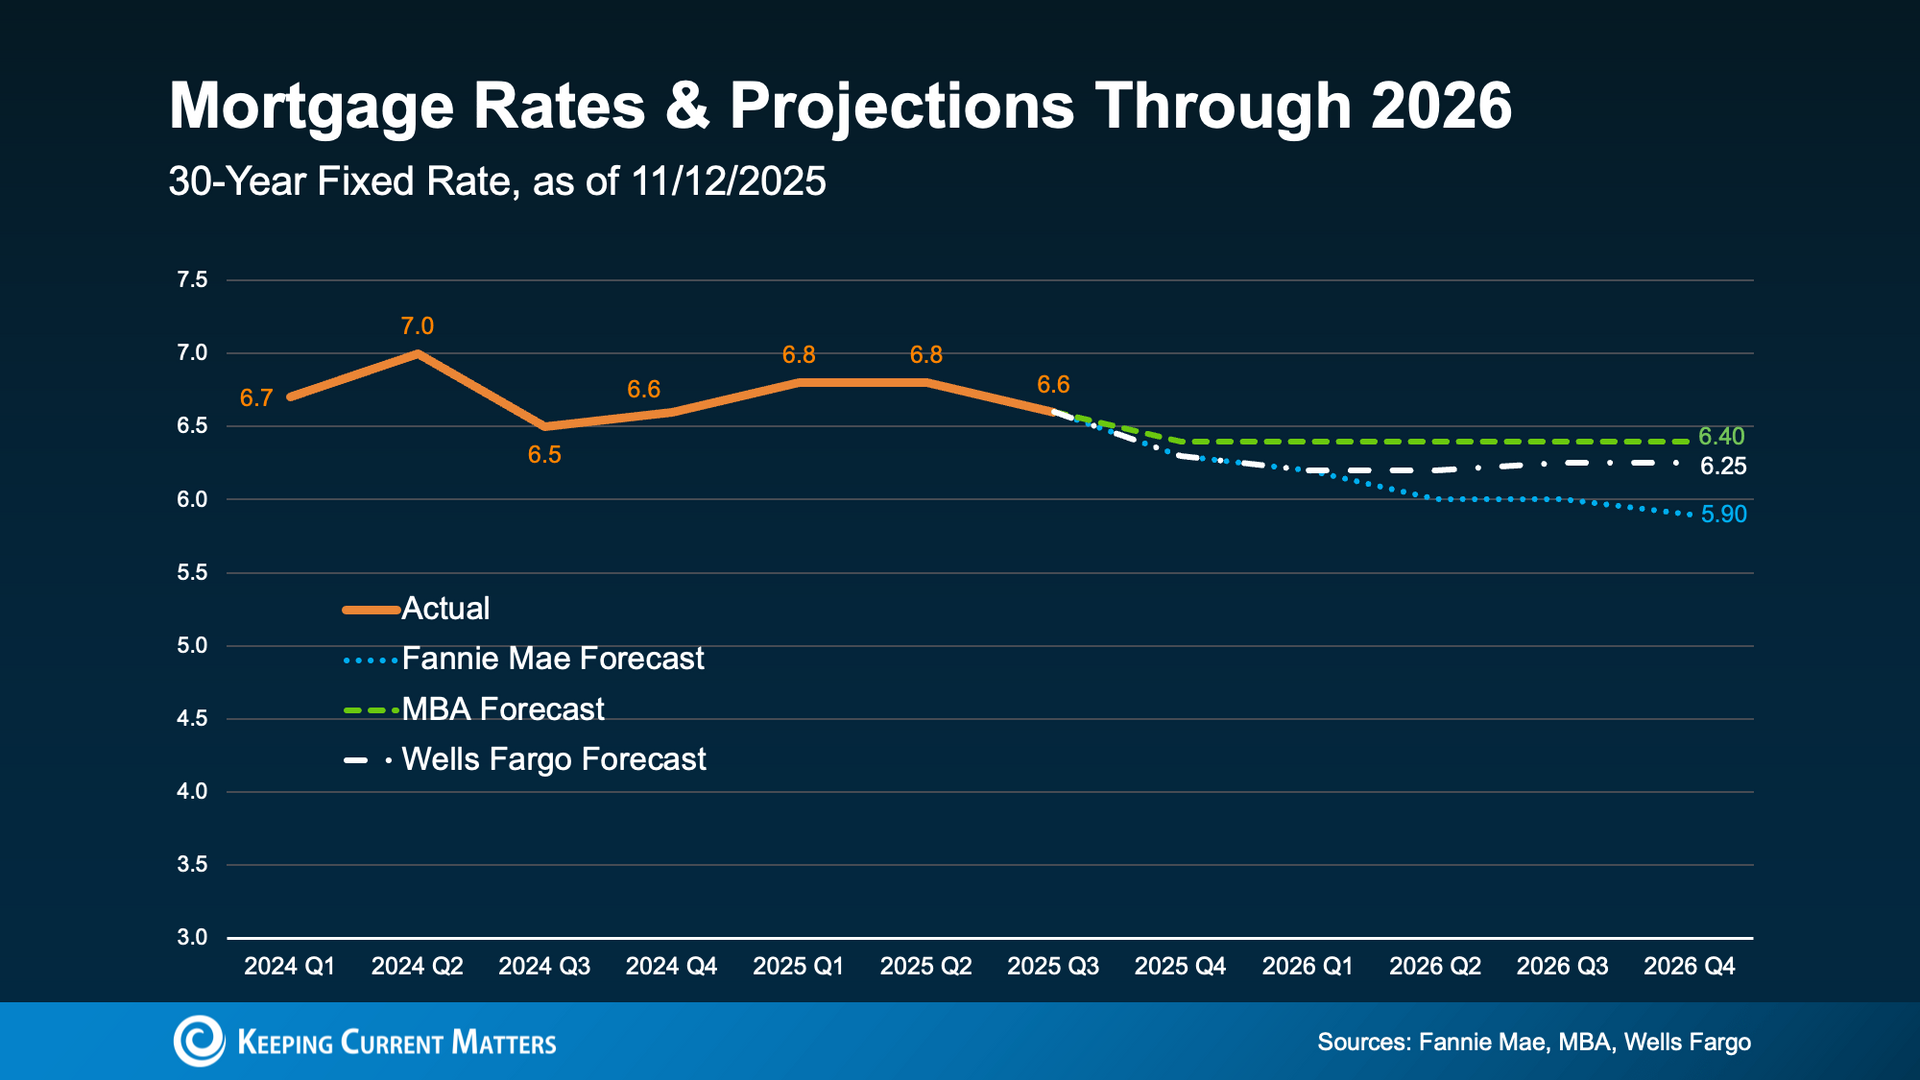
For starters, most experts say mortgage rates are likely to stay pretty much where we are today throughout 2026. So, there’s no guarantee we’ll see a rate much lower than what we have now. Only one expert forecaster is saying rates could fall into the upper 5s next year (see graph below): 

And even if rates do dip below 6%, the extra savings you’re holding out for won’t move the needle as much as you might expect.

The Real Math Behind a 5.99% Rate

Let’s break it down. If rates come down to 5.99% from where they’ve been lately that’s a difference of only about $80 a month on an average priced home – give or take a bit based on your price point and the rate your lender quotes you (see chart below):
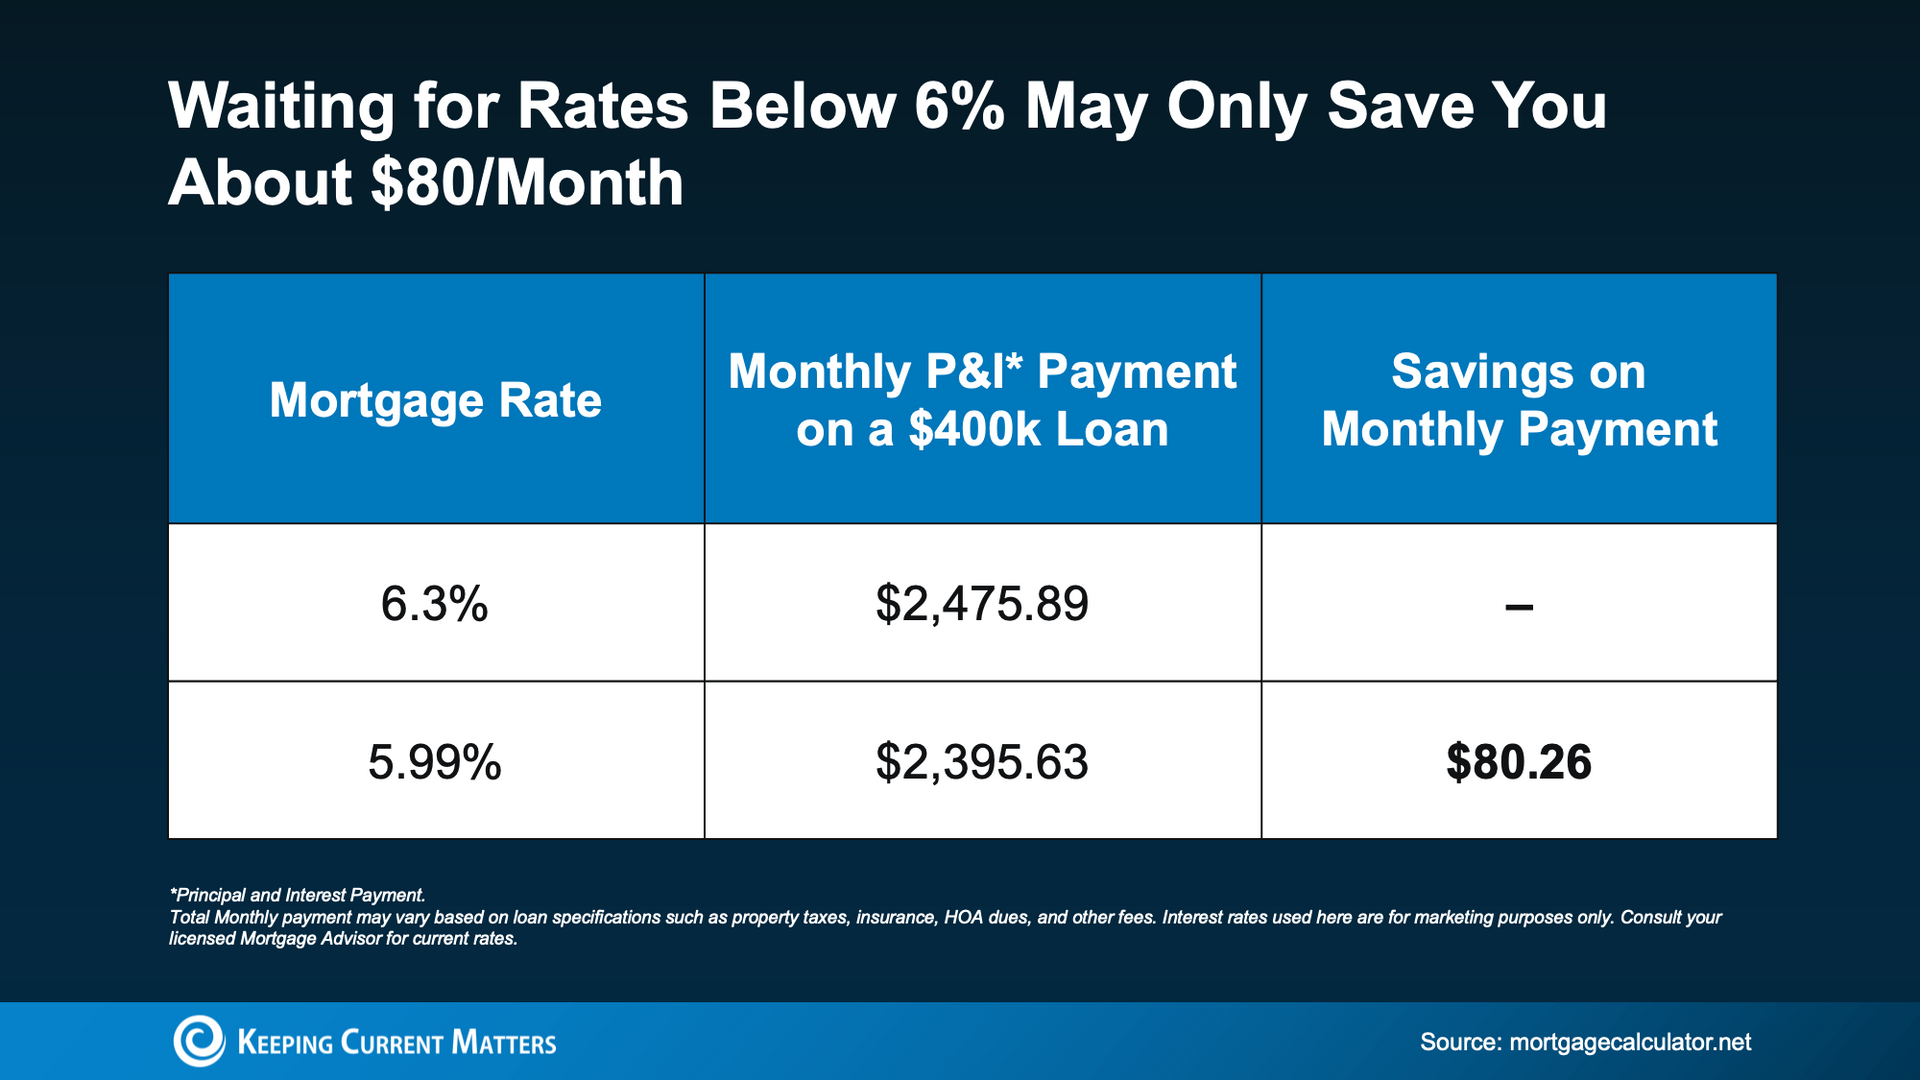
Eighty dollars. That’s it. And for the typical family, that’s about one dinner out (or one dinner in, if you have it delivered). That’s not enough to change the game for most buyers. But the savings of nearly $400 we already have compared to when you paused your search in the spring? That might be. 

So, the question to ask yourself is this:

Is an extra $80 savings really worth the wait?

Because while you’re holding out for that small dip, the bigger opportunity might be slipping away.


When Rates Fall, Competition Follows

Right now, you have more homes to choose from, sellers who are ready to negotiate to get a deal done, and fewer buyers to compete with. But once rates fall below 6%, buyer mindsets will shift and all of that will change.

The National Association of Realtors (NAR) reports that if rates hit 6%, about 5.5 million more households will be able to afford the median-priced home. Even if only a small fraction of them decide to buy, that could mean hundreds of thousands of buyers getting back into the market.

That creates more competition for you, which would push home prices even higher – maybe high enough to cancel out the extra savings you waited for.

So, if you’re waiting for rates below 6%, just keep in mind… that extra $80 may not be worth it in the grand scheme of things.


Bottom Line

You don’t have to wait for 5.99%. You have the chance to move (and save) right now. So, ask yourself: Would you let $80 hold you back from buying a home?

If you find a home you love and the math makes sense, getting ahead may be the best strategy. Connect with an agent or lender to run your numbers. That way you can see what you’re working with in your market.
By Brooke Thedford September 10, 2026
Ask a couple people how the housing market is doing and you’ll probably get a couple different answers. That’s because right now, the market runs on 2 very different tracks, split by price point. Knowing which track your house is on changes everything about your sale, from your asking price to how long you can expect to wait before an offer comes in. Here’s what you need to know. Home Sales Are Picking Up Speed at the Top of the Market Rates and buyer competition are shaping this market differently depending on price point. Look at recent sales data from the National Association of Realtors (NAR) and the pattern jumps right out. Homes priced under $250,000 saw sales drop 2-3% compared to last year, while homes priced above $750,000 saw sales climb by double digits (see graph below):
By Brooke Thedford September 9, 2026
Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is. Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything. Why Dipping into a 401(k) Can Be Tempting Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):
We’ve been busy this summer, but we’re back and refreshed with a new look! ☀️ Stay up to date with t
By Brooke Thedford August 25, 2026
We’ve been busy this summer, but we’re back and refreshed with a new look! ☀️ Stay up to date with the latest market updates, new listings, real estate insights, and more.
By Brooke Thedford August 18, 2026
Ask around, and almost every Houston homebuyer wants to know if there’s a way to get a better deal. And just about every Houston-area home seller wants to know if they’ll still get top dollar. The interesting thing is… both can be right at the exact same time. It just depends on where you live — and that’s especially true when looking at the Houston and Pearland real estate markets. That’s because today’s housing market isn’t moving in one direction anymore. Some markets clearly favor buyers. Others still favor sellers. But most are sitting somewhere in the middle. Knowing where your local real estate market stands can completely change the strategy you use to buy or sell a home — and the expectations you should have along the way. Whether you’re looking at homes for sale in Pearland or buying or selling elsewhere in the Houston real estate market, let’s break it down. One Number Tells You Who’s Got Leverage So how do you know which market you’re in? There’s one number that tells the story faster than anything else: the months’ supply of homes for sale. It’s the clearest signal of who’s got leverage – and what strategy you’ll need. Think of it like this. Imagine no additional homes were listed starting today. Months’ supply tells us how long it would take to sell everything that’s currently on the market based on today’s demand. Generally speaking, if months’ supply is: Fewer than 4 months: Sellers usually have the advantage. 4 to 6 months: Buyers and sellers are on more equal footing. More than 6 months: Buyers can usually negotiate for a better deal. Right now, the National Association of Realtors (NAR) data says that number is 4.6 and that puts the overall market back in balanced territory (see graph below):
By Brooke Thedford August 13, 2026
If you’re a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you start looking for your next home in the Houston area? There’s no single right answer. The best call depends on your finances, your local real estate market, and your timeline. And a trusted Houston-area real estate agent can help you weigh all of it. But in a lot of cases these days, selling first puts you in the stronger spot. The Advantages of Selling First Selling is usually the trickier half of a move today, so getting it done first clears your biggest hurdle. And that’s especially true right now, because there are more homes for sale than there are buyers, which means houses are taking longer to sell than they did a year or two ago. So how does leading with your sale pay off? Let’s start with the money. 1. You Won’t Get Stuck Paying Two Mortgages Buy before you sell, and you could end up carrying two mortgages at once. And especially since houses are staying on the market longer these days, that overlap may drag on for more time than you’d planned. And if unexpected repairs come up, it could get even more expensive. Selling first takes that risk off the table, so you’re not multitasking homeownership. As Ramsey Solutions puts it: “It’s best to sell your old home before buying a new one to avoid unnecessary risks and possible headaches.“ 2. You Can Use Your Equity To Fuel Your Move This is always true, but one of the biggest perks of selling first is that you’ll know exactly how much money you’re walking away with. And one of the big figures that matters in that conversation is how much equity you have in your current place. Equity is basically your house’s value minus what you still owe on your mortgage. And it adds up fast. According to Realtor.com, homeowners who’ve been in their home for 5 years have about $180,000 in equity on average. And those who’ve had their home for 6-10 years? They have over $340,000. After you sell, you can use that money to cover your down payment or even buy your next home in cash. And knowing that profit up front helps you plan your next move. 3. Your Offer Will Be Hard To Pass Up When your house is already sold, you don’t have to make your offer contingent on that sale. In a market where buyers are taking their time, that’s exactly what a seller wants to see. Picture it from the seller’s side. If their house has been sitting for a while, they’ll gravitate toward the offer most likely to close without a snag. That can also give you room to ask for a little more, like repairs, since a motivated seller would rather keep things moving than lose you and wait for another offer to come in. Your agent can help you make the most of your upper hand in that scenario. Is There a Catch? Selling first has its tradeoffs too, and it helps to see the pros and cons side by side before you decide. Here’s a quick breakdown based on information from Zillow (see visual below):
By Brooke Thedford August 12, 2026
After more than a year of headlines talking about how home prices are going to crash, the latest data shows that price growth may be starting to pick back up again. And depending on whether you’re buying or selling, that shift means something different for you. The Numbers May Be Starting To Turn For the past couple of years, home price growth has been moderating – cooling from around 7% in mid-2024, according to Redfin (see graph below). But look at the right side of that graph. The pace of that growth appears to have hit its low point and started to turn.
By Brooke Thedford March 24, 2026
There’s one decision you’re going to make when you sell that determines whether your house sells quickly, or it sits. Whether buyers make an offer, or scroll past it. Whether you walk away with the maximum return, or you end up cutting the price later. And that’s your asking price. The #1 Mistake Sellers Make Today: Trusting the Wrong Number If you’re thinking of moving and trying to figure out what your house may sell for, it’s tempting to start with an online home value tool. They’re fast, free, and easy. And you don’t have to talk to anyone. But here’s the problem: they don’t know your house. And that can be a bigger drawback than you realize. Where Online Estimates Fall Short Online tools often lag behind the market. They look in the rearview mirror, relying on closed sales and delayed information. And in that sense, they’re using incomplete data. That’s not a miss in how these systems are built. Some information just isn’t available online. Bankrate explains: “While these tools can be a useful starting point, keep in mind that they typically do not provide the most accurate pricing. Algorithms can only rely on the information available; they can’t account for things like a home’s condition or renovations made since the last public information was updated.” They can’t see: - The unique features that make your house special - All the work you’ve put in to keep it in good condition - Or, how in-demand your specific neighborhood is right now So, while they may do a good job in some cases, they can’t be as accurate as a local agent who has boots on the ground day in and day out. In a market where buyers have more options, a seemingly small margin of error can cost you thousands if you price too low, or weeks of lost momentum and time if you price too high. If you want to sell for the most money and in the least amount of time, you don’t want the fast answer on how to price your house. You want the right one. That’s why the savviest homeowners today don’t rely on algorithms when it actually matters. They rely on people, specifically trusted local agents. What an Expert Agent Brings to the Table  According to 1000WATT, sellers overwhelmingly believe real estate agents have the best sense of a home’s true value, far more than any automated tools.
By Brooke Thedford March 6, 2026
There’s finally a little good news for anyone who’s been priced out or sitting on the sidelines. Buying a home is getting more affordable. Monthly payments have started to come down, and the squeeze buyers have been feeling for the past few years is slowly loosening. Now, that doesn’t mean everyone can suddenly afford a home, but with how tough the market’s been, the improvement we’re seeing matters. Affordability Is Finally Moving in the Right Direction One of the best ways to see this shift is by looking at how much of a household’s income it takes to buy a home. According to Zillow, housing is typically considered affordable when it takes 30% or less of your monthly income to cover your expenses. That includes your mortgage payment, taxes, insurance, and basic maintenance. For the past few years, the math was well above that threshold, and it made buying a home unachievable for many. But now, we’re slowly moving back toward a balance. Zillow research shows it’s taking less of a typical household’s income to buy a home than it did just a few years ago (see graph below):
By Brooke Thedford January 17, 2026
Would-be homebuyers aren’t sitting on the sidelines because they don’t want to buy. They’re sitting out because they think they can’t. And sometimes, it’s their credit score that’s holding them back.
January 17, 2026
In 2025, affordability was the best it’s been in 3 years. And experts agree the momentum will keep going in 2026. And that’s based on their analysis of the key factors shaping the housing market in the year ahead: mortgage rates, inventory, and home prices. Lower Mortgage Rates Are Already Here Mortgage rates have already come down from their peak. By some counts, they dropped by almost a full percentage point over the course of the last year. And that’s a big deal, even if it doesn’t sound like it. But how low will they go? And should you wait for them to come down more? Here’s your answer. Forecasts suggest they’ll stay pretty much where they are now and hover in the low 6% range throughout 2026 (see graph below):
More Posts