The Top 2 Things Homeowners Need To Know Before Selling

Brooke Thedford • December 8, 2025

Here’s something you should know before you sell your house. The homeowners who win in today’s market aren’t the ones waiting it out or stepping back. They’re the ones who adapt from the start.
And here’s where the mismatch is coming from.

A few years ago, you could set any price and buyers would come running, no matter what the price tag said. Odds are, you’d still sell for over asking. But things are different now.


Buyers have more options than they’ve had in years, so they can afford to be more selective. If your price feels even a little high to them, it’ll get overlooked in a heartbeat.


And for the homeowners who had that happen, some end up pulling their listings instead of making a simple adjustment that could have changed everything. Which is a shame, honestly. Because a small price tweak is usually all it takes to bring buyers in and get the deal done.


According to HousingWire, the average price cut right now is just 4%.

Think about that. Other sellers are listing too high and giving up rather than dropping their price 4%. If they’d just started 4% lower, they may have already sold. So, before you list, talk to your agent about what’s working nearby. They’ll help you find the sweet spot that’s competitive, realistic, and still protecting your bottom line.


And here’s the kicker. If you’ve been in your home for a while, your equity gives you room to set your list price more competitively and still come out way ahead. Unfortunately, those other sellers didn’t seem to realize that.


2. Don’t Rush the Process

Another common misstep: expecting your house to sell in a weekend.

Many sellers right now remember when homes sold in as little as hours – and they expect that to happen today. But in most markets, that’s not the reality anymore.

It takes closer to 60 days to go from listed to sold, which is actually normal (see the gray in the graph below):
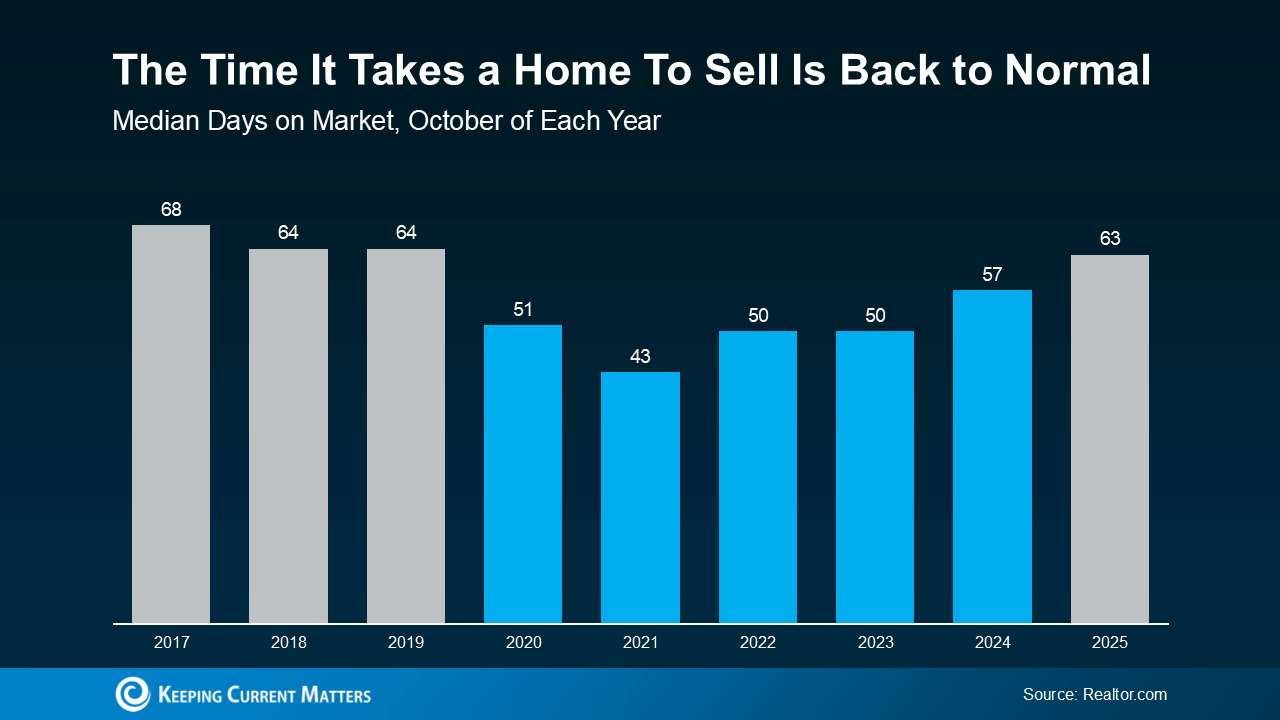
It just feels slower because they’re comparing it to the lightning-fast pace of 2020 and 2021.

Think of it like driving 65 mph on the highway, then exiting and going 25. It feels like you’re crawling, but it’s actually the right speed for where you are. That’s what other sellers can’t seem to get over. But you can get ahead of that, by knowing what to expect.

Today’s buyers are more intentional. They’re taking their time, weighing their options, and making thoughtful decisions, which is creating a much healthier housing market.

So, if you’re planning to sell, don’t expect it to happen instantly. And don’t assume your house won’t sell if it doesn’t go under contract in the first weekend.

It’s normal for these things to take time.

If you want to make sure your house sells as quickly as possible, talk to your agent about ways to stand out, whether that’s through staging, photography, or strategic pricing. With the right advice, the right price, and the right prep work, it can still sell quickly.

Bottom Line

If you’re thinking about selling, don’t let the market discourage you, let it guide you. The listings that didn’t sell this year weren’t doomed. They just started with the wrong strategy.

You can still win if you price right, are patient, and work with a local agent who knows how to position your home from the start.

Because in today’s market, success isn’t about waiting for conditions to change. It’s about getting your expectations right from day one.

A number of homeowners this year didn’t get the outcome they wanted. But it’s not because something’s wrong with the market. It’s because something wasn’t right with their expectations.


Realtor.com reports 57% more homes have been taken off the market compared to last year. That means they listed… but didn’t sell. But here’s the honest truth. It was mostly because of two things: price and timing.


And if the seller had come in with the right mindset on each, their sale would’ve gone differently. Here are the top 2 things you can learn from those other sellers.


1. Price It Right from Day 1

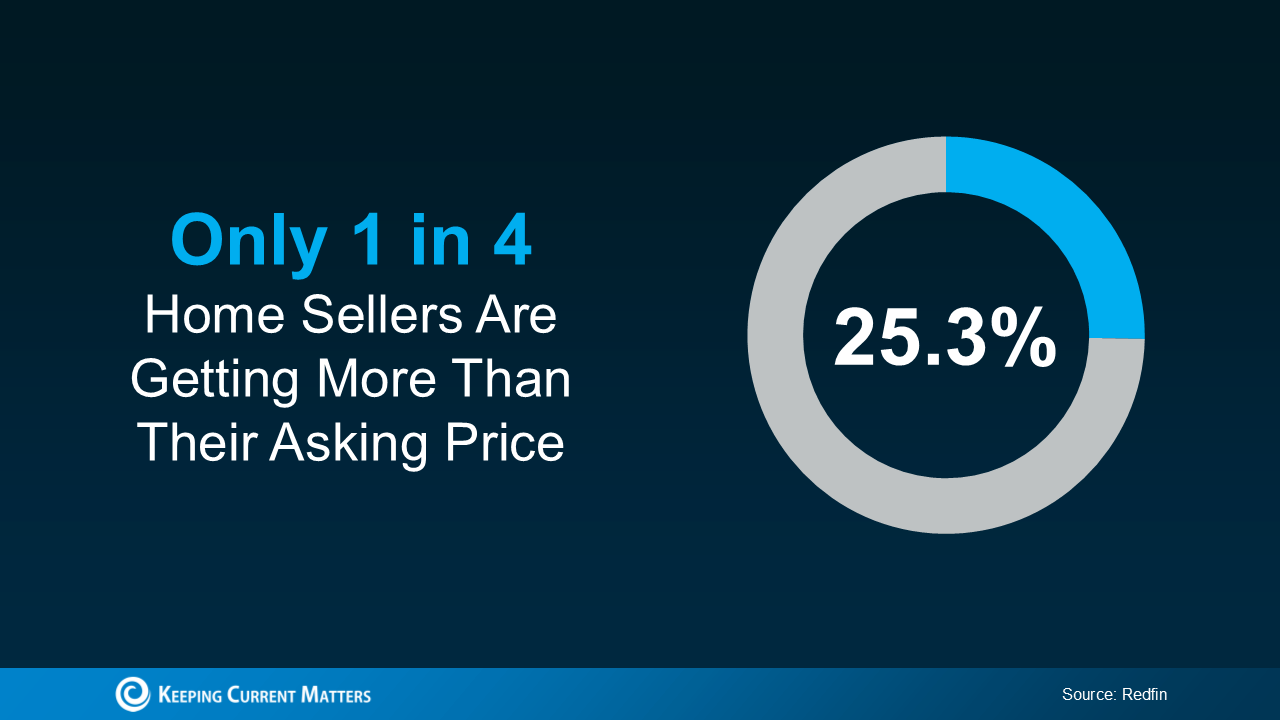
Let’s start with the most common sticking point: the asking price. Today, 8 in 10 sellers expect to get their asking price or more. But that confidence doesn’t always line up with reality.


According to Redfin, only 1 in 4 (25.3%) sellers are actually getting more than their list price.
By Brooke Thedford • October 1, 2026
By Brooke Thedford • September 30, 2026
You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a home, here’s what you need to remember… That’s not necessarily the number you’d get. It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about. What Determines Your Real Rate? Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that. That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at: Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate. Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be. The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage. The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs. Even after you find a home you love, other things can have an impact too. For example: A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy. Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate. There’s a lot that can ultimately have an impact on your actual rate. Your First Step? Getting Pre-Approved. If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be. Your lender may recommend a pre-qualification and pre-approval: Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information. On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information. Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:
By Brooke Thedford • September 10, 2026
Ask a couple people how the housing market is doing and you’ll probably get a couple different answers. That’s because right now, the market runs on 2 very different tracks, split by price point. Knowing which track your house is on changes everything about your sale, from your asking price to how long you can expect to wait before an offer comes in. Here’s what you need to know. Home Sales Are Picking Up Speed at the Top of the Market Rates and buyer competition are shaping this market differently depending on price point. Look at recent sales data from the National Association of Realtors (NAR) and the pattern jumps right out. Homes priced under $250,000 saw sales drop 2-3% compared to last year, while homes priced above $750,000 saw sales climb by double digits (see graph below):
By Brooke Thedford • September 9, 2026
Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is. Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything. Why Dipping into a 401(k) Can Be Tempting Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):
We’ve been busy this summer, but we’re back and refreshed with a new look! ☀️ Stay up to date with t
By Brooke Thedford • August 25, 2026
We’ve been busy this summer, but we’re back and refreshed with a new look! ☀️ Stay up to date with the latest market updates, new listings, real estate insights, and more.
By Brooke Thedford • August 18, 2026
Ask around, and almost every Houston homebuyer wants to know if there’s a way to get a better deal. And just about every Houston-area home seller wants to know if they’ll still get top dollar. The interesting thing is… both can be right at the exact same time. It just depends on where you live — and that’s especially true when looking at the Houston and Pearland real estate markets. That’s because today’s housing market isn’t moving in one direction anymore. Some markets clearly favor buyers. Others still favor sellers. But most are sitting somewhere in the middle. Knowing where your local real estate market stands can completely change the strategy you use to buy or sell a home — and the expectations you should have along the way. Whether you’re looking at homes for sale in Pearland or buying or selling elsewhere in the Houston real estate market, let’s break it down. One Number Tells You Who’s Got Leverage So how do you know which market you’re in? There’s one number that tells the story faster than anything else: the months’ supply of homes for sale. It’s the clearest signal of who’s got leverage – and what strategy you’ll need. Think of it like this. Imagine no additional homes were listed starting today. Months’ supply tells us how long it would take to sell everything that’s currently on the market based on today’s demand. Generally speaking, if months’ supply is: Fewer than 4 months: Sellers usually have the advantage. 4 to 6 months: Buyers and sellers are on more equal footing. More than 6 months: Buyers can usually negotiate for a better deal. Right now, the National Association of Realtors (NAR) data says that number is 4.6 and that puts the overall market back in balanced territory (see graph below):
By Brooke Thedford • August 13, 2026
If you’re a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you start looking for your next home in the Houston area? There’s no single right answer. The best call depends on your finances, your local real estate market, and your timeline. And a trusted Houston-area real estate agent can help you weigh all of it. But in a lot of cases these days, selling first puts you in the stronger spot. The Advantages of Selling First Selling is usually the trickier half of a move today, so getting it done first clears your biggest hurdle. And that’s especially true right now, because there are more homes for sale than there are buyers, which means houses are taking longer to sell than they did a year or two ago. So how does leading with your sale pay off? Let’s start with the money. 1. You Won’t Get Stuck Paying Two Mortgages Buy before you sell, and you could end up carrying two mortgages at once. And especially since houses are staying on the market longer these days, that overlap may drag on for more time than you’d planned. And if unexpected repairs come up, it could get even more expensive. Selling first takes that risk off the table, so you’re not multitasking homeownership. As Ramsey Solutions puts it: “It’s best to sell your old home before buying a new one to avoid unnecessary risks and possible headaches.“ 2. You Can Use Your Equity To Fuel Your Move This is always true, but one of the biggest perks of selling first is that you’ll know exactly how much money you’re walking away with. And one of the big figures that matters in that conversation is how much equity you have in your current place. Equity is basically your house’s value minus what you still owe on your mortgage. And it adds up fast. According to Realtor.com, homeowners who’ve been in their home for 5 years have about $180,000 in equity on average. And those who’ve had their home for 6-10 years? They have over $340,000. After you sell, you can use that money to cover your down payment or even buy your next home in cash. And knowing that profit up front helps you plan your next move. 3. Your Offer Will Be Hard To Pass Up When your house is already sold, you don’t have to make your offer contingent on that sale. In a market where buyers are taking their time, that’s exactly what a seller wants to see. Picture it from the seller’s side. If their house has been sitting for a while, they’ll gravitate toward the offer most likely to close without a snag. That can also give you room to ask for a little more, like repairs, since a motivated seller would rather keep things moving than lose you and wait for another offer to come in. Your agent can help you make the most of your upper hand in that scenario. Is There a Catch? Selling first has its tradeoffs too, and it helps to see the pros and cons side by side before you decide. Here’s a quick breakdown based on information from Zillow (see visual below):
By Brooke Thedford • August 12, 2026
After more than a year of headlines talking about how home prices are going to crash, the latest data shows that price growth may be starting to pick back up again. And depending on whether you’re buying or selling, that shift means something different for you. The Numbers May Be Starting To Turn For the past couple of years, home price growth has been moderating – cooling from around 7% in mid-2024, according to Redfin (see graph below). But look at the right side of that graph. The pace of that growth appears to have hit its low point and started to turn.
By Brooke Thedford • March 24, 2026
There’s one decision you’re going to make when you sell that determines whether your house sells quickly, or it sits. Whether buyers make an offer, or scroll past it. Whether you walk away with the maximum return, or you end up cutting the price later. And that’s your asking price. The #1 Mistake Sellers Make Today: Trusting the Wrong Number If you’re thinking of moving and trying to figure out what your house may sell for, it’s tempting to start with an online home value tool. They’re fast, free, and easy. And you don’t have to talk to anyone. But here’s the problem: they don’t know your house. And that can be a bigger drawback than you realize. Where Online Estimates Fall Short Online tools often lag behind the market. They look in the rearview mirror, relying on closed sales and delayed information. And in that sense, they’re using incomplete data. That’s not a miss in how these systems are built. Some information just isn’t available online. Bankrate explains: “While these tools can be a useful starting point, keep in mind that they typically do not provide the most accurate pricing. Algorithms can only rely on the information available; they can’t account for things like a home’s condition or renovations made since the last public information was updated.” They can’t see: - The unique features that make your house special - All the work you’ve put in to keep it in good condition - Or, how in-demand your specific neighborhood is right now So, while they may do a good job in some cases, they can’t be as accurate as a local agent who has boots on the ground day in and day out. In a market where buyers have more options, a seemingly small margin of error can cost you thousands if you price too low, or weeks of lost momentum and time if you price too high. If you want to sell for the most money and in the least amount of time, you don’t want the fast answer on how to price your house. You want the right one. That’s why the savviest homeowners today don’t rely on algorithms when it actually matters. They rely on people, specifically trusted local agents. What an Expert Agent Brings to the Table  According to 1000WATT, sellers overwhelmingly believe real estate agents have the best sense of a home’s true value, far more than any automated tools.
By Brooke Thedford • March 6, 2026
There’s finally a little good news for anyone who’s been priced out or sitting on the sidelines. Buying a home is getting more affordable. Monthly payments have started to come down, and the squeeze buyers have been feeling for the past few years is slowly loosening. Now, that doesn’t mean everyone can suddenly afford a home, but with how tough the market’s been, the improvement we’re seeing matters. Affordability Is Finally Moving in the Right Direction One of the best ways to see this shift is by looking at how much of a household’s income it takes to buy a home. According to Zillow, housing is typically considered affordable when it takes 30% or less of your monthly income to cover your expenses. That includes your mortgage payment, taxes, insurance, and basic maintenance. For the past few years, the math was well above that threshold, and it made buying a home unachievable for many. But now, we’re slowly moving back toward a balance. Zillow research shows it’s taking less of a typical household’s income to buy a home than it did just a few years ago (see graph below):
More Posts