The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.
You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a home, here’s what you need to remember…
That’s not necessarily the number you’d get. It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about.
What Determines Your Real Rate?
Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that.
That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at:
- Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.
- Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be.
- The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage.
- The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs.
Even after you find a home you love, other things can have an impact too. For example:
- A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.
- Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate.
There’s a lot that can ultimately have an impact on your actual rate.
Your First Step? Getting Pre-Approved.
If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be.
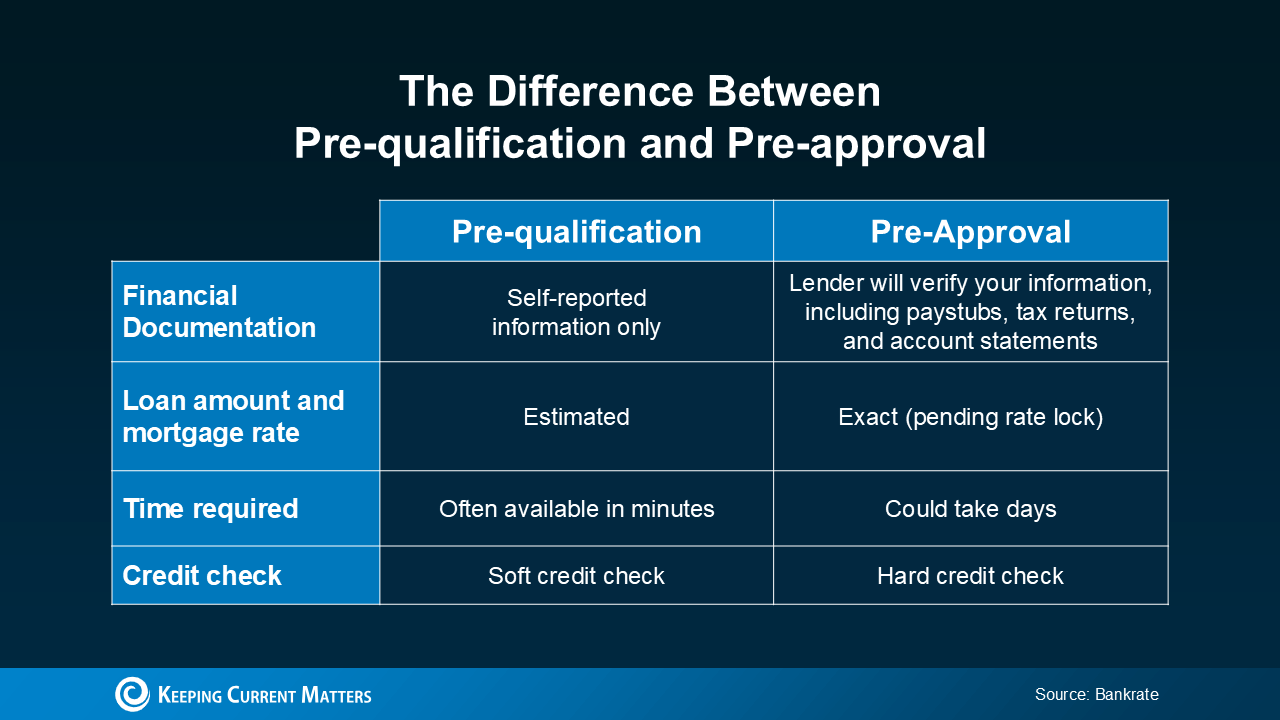
Your lender may recommend a pre-qualification and pre-approval:
- Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information.
- On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information.
Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:
How To Get Ready for the Conversation
If you’re thinking about buying a home in Houston, Pearland, or the surrounding area, start by asking your lender what documents you’ll need to gather. It’s also helpful to have a few questions ready so you can better understand what today’s mortgage rates mean for your specific homebuying plans.
Here are a few things to ask:
- What could I gain or lose by waiting 3, 6, or 12 months to buy a home in the Houston area?
- Are there any tax advantages to buying a home, and what could they mean for me?
- What are the benefits of buying now and starting to build home equity versus waiting?
- How could changes in mortgage rates affect my monthly payment and buying power?
- Based on my budget and current rates, what price range should I consider when looking at homes for sale in Pearland or Greater Houston?
Once you know the mortgage rate you may actually qualify for, you’ll have a much clearer picture of your options. Maybe buying a home now makes sense, or maybe waiting is the better fit for your situation. Either way, you can make that decision based on your own numbers instead of national headlines.
Bottom Line
Headlines and social media can make today’s mortgage rates feel intimidating, but the rate you see online may not be the rate you actually qualify for. If you’re considering buying a home in Pearland or the Greater Houston area, talking with a trusted lender is one of the best ways to understand your real buying power.
And when you’re ready to start your home search, working with a local Pearland real estate agent who understands the Greater Houston market can help you turn those numbers into a homebuying strategy that works for you.